PDF · 5.8 KB · Free
Retail KPI Cheat Sheet: 21 Formulas, Worked From One Store's Numbers
Twenty-one retail KPI formulas, each one stating what goes in its denominator, and every one of them computed from the same store’s figures so the numbers tie out.
The buy looked fine. A home category, 61.3 percent markup on cost, signed off on a Tuesday and cut to the vendor on the Thursday. Six weeks later the finance review put the same line at 38.0 percent, and the buyer and the analyst spent forty minutes arguing about which system was broken.
Neither was. Both numbers describe the same dollar spread on the same units. One divides that spread by cost and the other divides it by sales, and the two conventions produce percentages twenty three points apart from a single pair of dollar figures. Nothing on either report looked wrong. Nothing was flagged. The number was plausible, internally consistent, and useless for comparison with anything computed the other way.
That is the ordinary shape of a retail math error. It is almost never the arithmetic. It is the denominator, and a formula list that does not say what goes underneath the line will keep producing plausible wrong answers indefinitely. Every formula on this page states its inputs explicitly, and every one of them is computed from the same store’s figures so you can watch the numbers tie out.
Retail KPIs are calculated from four base figures: net sales, cost of goods sold, average inventory at cost, and units. Gross margin percentage is (Net Sales − COGS) ÷ Net Sales × 100, while markup percentage is (Net Sales − COGS) ÷ COGS × 100, which is why the same two dollar figures produce two different percentages. Every other retail KPI on this page is built from those four inputs plus one operational count.
Both files are free. No email, no signup, no wait.
Retail KPI Calculator
Twenty-one retail KPIs from one set of inputs. GMROI is the headline because it is the only metric here that moves when either half of the retail equation moves, and it is printed with its two decomposition factors so you can see which half is short.
Enter your numbers
Sales and margin
Sales after returns, discounts and allowances. Exclude sales tax.
Landed cost of the units actually sold in the period. Not the cost of what you bought.
Permanent and promotional markdowns at retail value, for the same period.
Inventory
Cost value at the first day of the period.
Cost value at the last day. Average inventory is calculated from these two.
Opening units plus units received. Needed for sell-through only.
Store and traffic
Selling floor only. Exclude stockroom, offices and back of house.
Completed sales transactions, not line items.
Total units across all transactions.
Entries counted at the door. Needed for conversion rate only.
Cost and labor
Wages plus payroll taxes and benefits, for store staff.
Full-time equivalents, not headcount. Two half-timers are one FTE.
The gap between book and counted inventory, valued at retail.
Supply
Inbound orders closed in the period.
Orders meeting both conditions. An order failing either one does not count.
Total lines across all inbound orders.
Lines delivered at full requested quantity.
Your calculation
GMROI
$2.46
Gross Margin %
38.0%
Markup % on Cost
61.3%
Inventory Turnover
4.01 turns
Days Inventory Outstanding
91 days
Sell-Through Rate
84.3%
Sales per Square Foot
$257.50
Formula Used
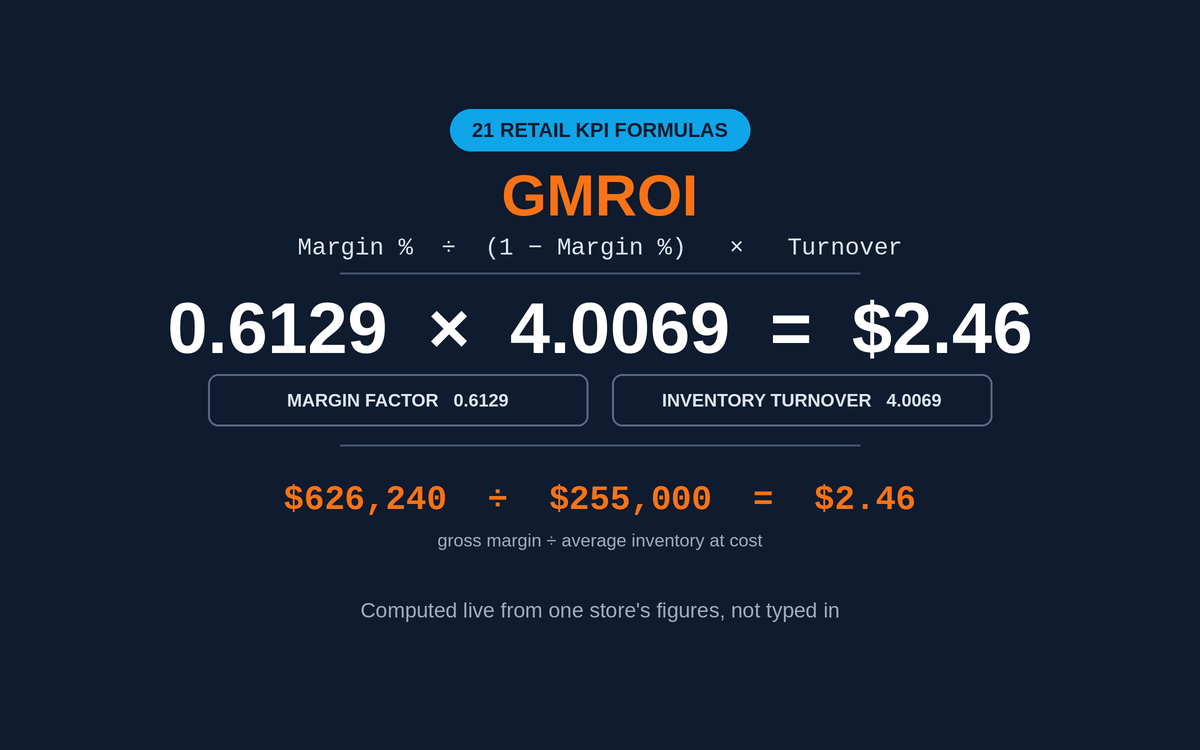
GMROI = Gross Margin $ ÷ Average Inventory at Cost, where Gross Margin $ = Net Sales − COGS and Average Inventory at Cost = (Beginning Inventory + Ending Inventory) ÷ 2
GMROI = [ Gross Margin % ÷ (1 − Gross Margin %) ] × Inventory Turnover = 0.61 × 4.01
Interpretation & Recommendations
| Metric | Formula | Your value |
|---|---|---|
| Gross margin $ | Net Sales − COGS | $626,240 |
| Gross margin % | Gross Margin $ ÷ Net Sales × 100 | 38.0% |
| Markup % on cost | Gross Margin $ ÷ COGS × 100 | 61.3% |
| Markdown rate % | Markdowns ÷ Net Sales × 100 | 6.25% |
| Average transaction value | Net Sales ÷ Transactions | $40.00 |
| Units per transaction | Units Sold ÷ Transactions | 1.80 |
| Conversion rate % | Transactions ÷ Traffic × 100 | 20.0% |
| Sales per square foot | Net Sales ÷ Selling Area | $257.50 |
| Sales per employee | Net Sales ÷ Average FTE | $103,000 |
| Inventory turnover | COGS ÷ Average Inventory at Cost | 4.01 turns |
| Days inventory outstanding | 365 ÷ Inventory Turnover | 91 days |
| GMROI | Gross Margin $ ÷ Average Inventory at Cost | $2.46 |
| Sell-through rate % | Units Sold ÷ Units Available × 100 | 84.3% |
| Average inventory at retail | Average Inventory at Cost ÷ Cost Complement | $411,290 |
| Stock-to-sales ratio | Average Inventory at Retail ÷ Monthly Sales | 3.0 |
| Weeks of supply | Average Inventory at Retail ÷ Weekly Sales | 13.0 wks |
| Cost complement % | COGS ÷ Net Sales × 100 | 62.0% |
| Shrink rate % | Shrink at Retail ÷ Net Sales × 100 | 1.5% |
| Labor cost % | Payroll ÷ Net Sales × 100 | 13.0% |
| OTIF % | Orders On Time AND In Full ÷ Total Orders × 100 | 89.0% |
| Fill rate % | Lines Shipped Complete ÷ Lines Requested × 100 | 95.5% |
What's inside
- All 21 formulas printed on the page, not locked inside the download
- What each input actually means, so the denominator is never a guess
- Every metric computed from one store’s figures, so the numbers tie out
- A live widget that runs your own numbers through all 21
- Three denominator traps, each with the size of the error it causes
- Which metrics to read weekly, which monthly, and which only at season close
- No benchmark ranges, because no citable public dataset of them exists
The twenty-one formulas
Four groups. Each row gives the metric, the formula, what the inputs actually mean, and the value for the worked-example store below. Rows link to the calculator that computes them, where one exists.
Sales and margin
| Metric | Formula | What the inputs mean | Northgate Home |
|---|---|---|---|
| Gross margin $ | Net Sales − COGS | COGS is the cost of units sold, not units bought | $626,240 |
| Gross margin % | Gross Margin $ ÷ Net Sales × 100 | Denominator is sales. Gross margin calculator | 38.0% |
| Markup % on cost | Gross Margin $ ÷ COGS × 100 | Denominator is cost. Same spread, different base. Markup calculator | 61.3% |
| Markdown rate % | Markdowns ÷ Net Sales × 100 | Markdowns at retail value, sales net of them | 6.25% |
| Average transaction value | Net Sales ÷ Transactions | Transactions, not line items | $40.00 |
| Units per transaction | Units Sold ÷ Transactions | Same denominator as ATV | 1.80 |
| Conversion rate % | Transactions ÷ Traffic × 100 | Traffic is door entries, not sessions | 20.0% |
| Sales per square foot | Net Sales ÷ Selling Area | Selling floor only, stockroom excluded | $257.50 |
| Sales per employee | Net Sales ÷ Average FTE | FTE, not headcount. Sales per employee calculator | $103,000 |
Inventory
| Metric | Formula | What the inputs mean | Northgate Home |
|---|---|---|---|
| Inventory turnover | COGS ÷ Average Inventory at Cost | Both sides at cost. Inventory turnover calculator | 4.01 turns |
| Days inventory outstanding | 365 ÷ Inventory Turnover | Reciprocal of turnover, scaled to a year. DIO calculator | 91 days |
| GMROI | Gross Margin $ ÷ Average Inventory at Cost | Margin at retail over inventory at cost, deliberately. GMROI calculator | $2.46 |
| Sell-through rate % | Units Sold ÷ Units Available × 100 | Available is opening plus received, not just received. Sell-through calculator | 84.3% |
| Average inventory at retail | Average Inventory at Cost ÷ (1 − Gross Margin %) | The cost complement converts one to the other | $411,290 |
| Stock-to-sales ratio | Average Inventory at Retail ÷ Monthly Sales | Both sides at retail. Mixing bases is the usual error | 3.0 |
| Weeks of supply | Average Inventory at Retail ÷ Weekly Sales | Same ratio as stock-to-sales on a weekly clock | 13.0 weeks |
Cost and loss
| Metric | Formula | What the inputs mean | Northgate Home |
|---|---|---|---|
| Cost complement % | COGS ÷ Net Sales × 100 | Simply 100 minus gross margin % | 62.0% |
| Shrink rate % | Shrink at Retail ÷ Net Sales × 100 | Both at retail. A cost-valued shrink over retail sales understates it | 1.5% |
| Labor cost % | Payroll ÷ Net Sales × 100 | Payroll including taxes and benefits. Productivity calculator | 13.0% |
Supply
| Metric | Formula | What the inputs mean | Northgate Home |
|---|---|---|---|
| OTIF % | Orders On Time AND In Full ÷ Total Orders × 100 | An order failing either condition fails both. OTIF calculator | 89.0% |
| Fill rate % | Lines Shipped Complete ÷ Lines Requested × 100 | Line level, which is why it reads higher than OTIF | 95.5% |
Two rows carry no link on purpose: there is no fill rate calculator and no stock-to-sales calculator on this site, so nothing is linked rather than linking somewhere approximate.
How the number is calculated
GMROI = Gross Margin $ ÷ Average Inventory at Cost, where Gross Margin $ = Net Sales − COGS and Average Inventory at Cost = (Beginning Inventory + Ending Inventory) ÷ 2
Twenty-one formulas sounds like twenty-one things to learn. It is four. Net sales, cost of goods sold, average inventory at cost, and a unit count. Every metric here is one of those divided by another of those, or by a physical count of something in the store: square feet, transactions, door entries, staff, order lines. Once you can produce those four cleanly, the rest is division. Producing them cleanly is the part that goes wrong. Net sales means after returns, after discounts, after allowances, and without sales tax. A POS export labelled "sales" is often gross, and a gross sales figure inflates every ratio here that carries sales in the denominator, quietly and in the flattering direction. Cost of goods sold means the landed cost of what actually sold in the period. It is not the cost of what you purchased in the period, and in any month where receipts and sales are out of step those two figures differ enough to move turnover by half a turn. Why margin and markup are not the same percentage is the single most expensive confusion in retail math, and it is worth being slow about. Take one line. It cost $100 and it sells for $161.29. The spread is $61.29. That spread expressed against cost is a 61.3 percent markup. The same spread expressed against the selling price is a 38.0 percent margin. Both statements are true, both describe the identical transaction, and there is no arithmetic error anywhere. The conversions are Markup % = Margin % ÷ (1 − Margin %) and Margin % = Markup % ÷ (1 + Markup %). The damage happens when someone buys to a target expressed in the wrong convention. A buyer told to protect a 38 percent margin who buys at 38 percent markup on cost lands at 0.38 ÷ 1.38, which is a 27.5 percent margin. That is 10.5 margin points short of the target, on every unit, discovered a season later. The gross margin vs markup guide works through the conversion table in both directions, and the gross margin and markup calculators will do it on a single line. Some categories quote a third convention, keystone, meaning a 100 percent markup on cost, which is a 50 percent margin. When a vendor says keystone and a planner hears 50 points, they happen to agree. When a vendor says 40 percent and a planner hears 40 points, they do not. Average inventory appears in three formulas here and almost every published cheat sheet leaves it undefined. The two-point average of beginning and ending inventory is what almost everyone uses, and it is what this page uses: (268,000 + 242,000) ÷ 2 = $255,000. It is defensible for a full year in a business without violent seasonality. It is poor for a quarter that contains a peak, and close to meaningless for a single month, because a two-point average of a curve with a spike in the middle is not the average of the curve. The alternative is a thirteen-point average, the twelve month-end balances plus the opening balance, divided by thirteen. If your system can produce it, use it, and say on the report which one you used. Substituting ending inventory for average inventory is the common shortcut, and it flatters. For this store, turnover on ending inventory reads 4.22 instead of 4.01, and GMROI reads $2.59 instead of $2.46. Both overstate performance by 5.4 percent, and the overstatement is not random: it grows every time inventory is drawn down late in the period, which is exactly what a store does going into a slow season. So the shortcut is most flattering in the periods you were most likely to have underperformed. Then there is the basis question. Inventory turnover has two constructions. At cost it is COGS over average inventory at cost. At retail it is net sales over average inventory at retail. Published formula lists print one or the other and rarely say which. For this store they agree exactly: at cost, 1,021,760 ÷ 255,000 = 4.01, and at retail, 1,648,000 ÷ 411,290 = 4.01. That agreement is not a validation. It happens because a single uniform cost complement of 62.0 percent was applied to convert one side to the other, so the same ratio appears on both sides of the conversion by construction. They separate the moment realized margin diverges from the margin assumed in the conversion, which is precisely what markdowns and mix shift do all season. A store carrying a fashion classification at 55 percent planned margin that actually realizes 41 percent after clearance has an inventory-at-retail figure derived from an assumption its own P&L already contradicted. The retail inventory method guide covers how that conversion is built and where it drifts. The practical rule: pick the cost construction when you can get clean COGS, keep it, and never compare a cost-basis turn to a retail-basis turn across stores or years. GMROI puts a retail-basis numerator over a cost-basis denominator on purpose, which offends people the first time they see it. Gross margin dollars are earned at retail. Average inventory is the money actually tied up, which is a cost figure. The ratio answers a cash question: for every dollar of capital sitting in stock across the year, how many dollars of gross margin came back. It decomposes exactly into margin and turnover, since 0.38 ÷ 0.62 = 0.6129 and 0.6129 × 4.01 = $2.46. That identity is the reason GMROI is the primary output here. Two stores can post the same GMROI from opposite operating models, and the decomposition tells you which one you are running before you decide what to change. There is more on reading the two factors against each other in the GMROI guide, and the GMROI calculator computes the ratio directly. Four metrics here depend on a physical count rather than a ledger figure, and each has a definitional trap of its own. Selling area means the selling floor. Including the stockroom, the receiving bay and the manager's office in the denominator will drag sales per square foot down by a quarter or more and make a productive store look weak against its own history the year someone remeasured. Transactions means completed sales, not line items, which is what separates average transaction value from average line value. Traffic means door entries, and a door counter that counts staff, deliveries and the same customer twice will hold conversion rate down permanently. Average FTE means full-time equivalents, not headcount: two people at twenty hours are one FTE, and a store that flexes heavily on part-time labor will read very differently on the two bases. Sales per employee is only comparable across stores when every store computes FTE the same way. OTIF and fill rate measure different failures. OTIF is order level and unforgiving by design. An order arriving on time with one line short fails, and an order arriving complete a day late fails. Fill rate is line level, so the same delivery scores most of its lines as successes. For this store, OTIF reads 89.0 percent against a fill rate of 95.5 percent, and the gap between the two numbers is the useful part: it says the failures are scattered across many orders rather than concentrated in a few bad ones. Two suppliers with identical fill rates can have very different OTIF, and the one with the lower OTIF is the one disrupting more of your receiving days. The OTIF calculator computes both conditions separately so you can see which one is failing. The full argument about which denominator belongs under which line, and which convention should have authority when a target passes between buying and finance, is in the denominator problem.
Worked example: Northgate Home, one store, one fiscal year
Northgate Home is an illustrative store, not a real retailer. The figures are a teaching dataset chosen to be internally consistent, so every metric can be computed from one set of inputs and the numbers tie out. The period is a full fiscal year, so days inventory outstanding uses 365 days and weeks of supply uses 52 weeks. Run a quarter or a month through the widget and those two change with it. The inputs are the ones pre-filled above: net sales $1,648,000, COGS $1,021,760, beginning inventory at cost $268,000, ending inventory at cost $242,000, which averages to $255,000. Gross margin dollars are 1,648,000 − 1,021,760 = $626,240, a 38.0 percent margin and a 61.3 percent markup on cost from the same spread. Inventory turnover is 1,021,760 ÷ 255,000 = 4.01 turns, and GMROI is 626,240 ÷ 255,000 = $2.46. A store with $626,240 of gross margin dollars and $255,000 of average inventory at cost has a GMROI of $2.46, meaning every dollar tied up in inventory returned $2.46 in gross margin over the year. The decomposition closes exactly: a margin factor of 0.38 ÷ 0.62 = 0.61 times 4.01 turns returns the same $2.46. Now the what-ifs. First, let margin fall four points, 38.0 percent to 34.0 percent, with net sales holding at $1,648,000 and average inventory unchanged, so COGS rises to $1,087,680. Gross margin dollars fall to $560,320 and GMROI falls to $2.20. Four margin points cost 26 cents of gross margin per dollar of inventory. Note that turnover measured at cost actually rises to 1,087,680 ÷ 255,000 = 4.27, because COGS went up while inventory did not, so a turnover report alone would show this store improving in the year its margin fell. Second, hold sales and margin and cut inventory 10 percent, so average inventory falls to $229,500. Turnover rises to 4.45 turns and GMROI rises to $2.73. A 10 percent inventory cut produces an 11.1 percent GMROI gain rather than a 10 percent one, because the denominator shrank rather than the numerator growing. Third, both together: margin at 34.0 percent and inventory down 10 percent gives 560,320 ÷ 229,500 = $2.44. A 10 percent inventory reduction does not pay for a four point margin loss, because $2.44 sits below the $2.46 baseline. That is the arithmetic that settles the argument in the markdown meeting. One more check worth running on your own numbers: using ending inventory of $242,000 instead of average inventory of $255,000 raises reported inventory turnover from 4.01 to 4.22 and GMROI from $2.46 to $2.59, overstating both by 5.4 percent.
Denominator traps
Three errors, each shown as the size of the mistake it makes rather than as a caution.
Trap 1. Margin against sales, reported as markup. The spread of $626,240 against sales of $1,648,000 is 38.0 percent. The same spread against cost of $1,021,760 is 61.3 percent. If a buyer protects the 38 by buying at 38 percent markup on cost, the realized margin is 0.38 ÷ 1.38 = 27.5 percent, which is 10.5 margin points below target. The error is invisible on the buy sheet and only surfaces in the season’s gross margin.
Trap 2. Ending inventory in place of average. Turnover reads 4.22 rather than 4.01, GMROI reads $2.59 rather than $2.46, and both overstate by 5.4 percent. The shortcut flatters hardest in periods that ended with a drawdown, which are usually the periods that went badly.
Trap 3. Comparing a cost-basis turn to a retail-basis turn. Both constructions return 4.01 for this store because a single uniform cost complement converted one to the other. They diverge as soon as realized margin differs from the assumed complement, which markdowns guarantee. Two stores can report turnover on different bases and appear to differ by a full turn when they are operating identically. Fix the basis, write it on the report, and never mix them in a comparison.
How to use these weekly
Four numbers on Monday, for a store manager: conversion rate, average transaction value, units per transaction, and sales per square foot against the same week last year. These move on execution, and they move within a week.
Monthly, for a buyer or planner: gross margin percentage, inventory turnover, GMROI, weeks of supply, and markdown rate. These move on decisions made four to twelve weeks earlier, so reading them weekly produces noise and false alarms. The retail KPI guide covers how to set the review cadence by role rather than by metric.
At season close, and only then: sell-through rate and stock-to-sales. Sell-through mid-season without a plan curve to compare against tells you almost nothing, since 60 percent through is excellent at week four and alarming at week eleven. The sell-through rate guide sets out how to build that curve.
Shrink rate arrives on whatever schedule your physical counts do, which for most stores is one or two points a year. Everything else here is diagnostic, pulled when a specific question needs answering rather than read on a schedule.
Related tools
Each formula row above links to the calculator that computes it, so the natural next step from any line is the tool for that line. Beyond those, the markdown calculator works the other direction from the markdown rate on this page and tells you what a proposed cut does to realized margin, which is the input to the first what-if above. The days inventory outstanding calculator is the same arithmetic as turnover expressed in days for anyone who reads working capital in days rather than turns, and the working capital guide explains why the two audiences differ. For gross margin by category against published sector data, the gross margin benchmarks draw on NYU Stern’s margins-by-sector dataset, which is a real citable source, unlike the KPI benchmark ranges that circulate without one. The retail KPI formulas workbook is the same 21 formulas as live Excel cells, and the retail KPI scorecard template is where these metrics go once you want them tracked period over period rather than computed once.
The longer argument about why the two conventions exist, and which one should have authority when a target passes between buying and finance, is in why two people calculate the same store differently.
Frequently Asked Questions
Why do markup and margin give different percentages from the same two numbers?+
Because they divide the same dollar spread by different denominators. Markup divides by cost, margin divides by sales, and since sales is always the larger figure the margin percentage is always the smaller one. A $61.29 spread on a $100 cost item selling at $161.29 is a 61.3 percent markup and a 38.0 percent margin. Convert between them with Markup = Margin ÷ (1 − Margin), or use the gross margin vs markup guide for the full conversion table.
Should inventory turnover use COGS or net sales?+
Use COGS over average inventory at cost. Both sides of that ratio are then on the same basis, which is what makes the answer meaningful. The retail construction, net sales over average inventory at retail, is valid but only if your inventory-at-retail figure comes from an actual retail-priced count rather than from converting a cost figure with an assumed margin. Whichever you pick, write it on the report, because a cost-basis turn and a retail-basis turn are not comparable.
Which inventory figure goes in the denominator: beginning, ending, or average?+
Average, and for a full year the two-point average of beginning and ending is usually adequate. For a quarter containing a peak, or for any single month, use the thirteen-point average if your system produces it. Using ending inventory alone overstates this store's turnover by 5.4 percent, and the overstatement is largest in periods that closed with a drawdown.
Is a GMROI of 2.5 good?+
There is no honest single answer, and any page giving you one without naming its data source is guessing. What can be said definitionally: below $1.00, the inventory returned less gross margin across the period than the average capital tied up in it. Above that, whether the number is adequate depends on your carrying cost, your cost of capital and your markdown exposure. The useful move is to decompose it. GMROI equals [Margin ÷ (1 − Margin)] × Turnover, so a $2.46 result built from 0.61 and 4.01 is a different business from the same result built from 1.22 and 2.01. Compare against your own prior period and against the same category in your own stores, not against a number from the internet.
When should I measure sell-through instead of inventory turnover?+
When the buy is finite. Sell-through measures a finite buy against itself: units sold divided by units available, answering "how much of what I bought has gone". Turnover measures flow against a standing position: cost of goods sold divided by average inventory, answering "how many times did I cycle my stock". So sell-through is the right reading on a seasonal or limited buy, and turnover is the right reading on continuity lines that are replenished. A basic never runs out of "available" units to sell through, so sell-through on it is close to meaningless. The sell-through calculator and the inventory turnover calculator compute each from its own inputs.
How do I convert a target margin into the markup I should buy at?+
Divide the target margin by one minus the target margin. A 38 percent margin target needs a 61.3 percent markup on cost, since 0.38 ÷ 0.62 = 0.613. A 40 percent target needs 66.7 percent, and a 50 percent target needs 100 percent, which is where the word keystone comes from. Do this conversion before the buy, not after, because the gap is not recoverable once the goods are costed in.
When does stock-to-sales tell me something turnover does not?+
When you need to know whether the stock you are holding right now is sized for what is about to happen, rather than what already did. Turnover is a backward-looking rate across a whole period. Stock-to-sales is a point-in-time ratio of inventory on hand to the sales rate you are planning for, so it is what an open-to-buy calculation actually consumes. A store can post acceptable annual turnover while sitting on the wrong stock-to-sales going into its biggest month. Open-to-buy planning covers how the ratio feeds the buy.
Do these formulas change for ecommerce?+
The financial ones do not. Gross margin, markup, turnover, GMROI and sell-through are identical. The store-operations ones need substitution: sales per square foot has no meaning without a floor, and conversion rate switches from door entries to sessions, which changes what the number means far more than it changes the formula. A physical door count is close to one count per visitor; sessions are not, because one shopper generates several across devices and days. Ecommerce conversion rates therefore read lower than store conversion rates as a matter of measurement, not performance, and the two should never be compared directly.
My POS reports a different gross margin than this formula. Which is wrong?+
Probably neither, and the difference is almost always one of three things. First, the POS may be reporting on gross sales while you are computing on net, which inflates the denominator. Second, the POS cost field is often last purchase cost or standard cost rather than the landed cost of the units actually sold, which is what COGS means. Third, many systems report margin before shrink and before markdown allowances, so the figure is a planned margin rather than a realized one. Reconcile by rebuilding both numbers from the same two inputs and finding which of the two moved.
Can I use these on a single category instead of a whole store?+
Yes, and category level is where most of them are actually useful, since a store-level GMROI averages a fast basic against a slow special order and hides both. Two cautions. Shared costs do not allocate cleanly, so labor cost percentage and sales per square foot need an allocation rule you state and keep. And a category with heavy transfers in or out will distort units available, which pushes sell-through around without anything real changing. Inventory aging analysis covers reading a category position when the aggregate looks healthy.
Related Calculators
GMROI Calculator
The single most honest cross-category profitability metric in retail. GMROI answers one question: for every dollar of inventory you funded, how many dollars of gross profit did you get back? A high [gross margin](/calculators/retail-finance/gross-margin-calculator) on inventory that never sells produces zero return, which is why GMROI keeps [margin](/calculators/retail-finance/gross-margin-calculator) and [inventory turnover](/calculators/inventory-management/inventory-turnover-calculator) honest against each other. The output is the GMROI ratio with gross margin percent, inventory turnover, gross profit and a plain-English performance band, because the ratio on its own tells a buyer very little.
Gross Margin Calculator
The cleanest read on how much of every sales dollar you actually keep after paying for the goods. Gross margin drives every downstream financial decision in retail: what to price, what to promote, what to keep on the shelf. Margin percent, the markup equivalent, cost as a percent of revenue and the price-to-cost multiplier all appear together, which is what it takes to translate between the three lenses without reaching for a second tool. The COGS input behind all of it depends on how inventory is valued in the first place, and a retailer using the [retail inventory method](/blog/retail-inventory-method-explained) will get a different COGS figure than one costing at actual unit cost, even from identical sales and purchase data.
Markup Calculator
Set a selling price from cost or reverse-engineer the markup baked into an existing price. Markup is the buyer’s language of pricing (percent added on top of cost), while [margin](/calculators/retail-finance/gross-margin-calculator) is the finance language (percent kept from revenue). Alongside markup percent come profit per unit, the margin equivalent and the price-to-cost multiplier. Buying and finance can then argue about the price rather than about the denominator. Departments already running the [retail inventory method calculator](/calculators/inventory-management/retail-inventory-method-calculator) have a cost-to-retail ratio on hand, which doubles as a fast sanity check against the markup this page returns.
Inventory Turnover Calculator
Measure how many times a year your average inventory sells through and gets replaced. The single most consequential operational KPI in retail. It connects buying decisions, warehouse cash, markdown risk, and finance targets into one number. The turn ratio arrives converted into days and weeks of supply, together with the working capital a one-turn improvement would release. Departments that carry stock at retail value rather than cost usually track it with a [retail inventory method tracking template](/templates/retail-inventory-method-template), which produces the same average-inventory figure this calculator needs.
Sell-Through Rate Calculator
The speed-of-sale metric every buyer, planner and category manager reads before touching pricing or reorder decisions. Sell-through rate measures the percent of received units that actually sold across the measurement window. High sell-through means the buy is working. Low sell-through means the inventory is aging faster than expected and the [markdown clock](/calculators/retail-finance/markdown-calculator) is running. Enter units sold and units received and the STR percent arrives next to remaining units, weekly sell rate, and projected weeks to both 80 percent and 100 percent sell-through, with a plain-English band saying whether the buy is on pace. The point of the band is to be acted on, not filed.
Productivity Calculator
Sales per labor hour (SPLH) is the most operationally actionable productivity metric in retail because it moves at the same weekly cadence store managers use to build schedules. Unlike sales per FTE, which is best suited to quarterly or annual comparisons, SPLH responds to the exact staffing decisions a manager makes for next week's schedule. It produces SPLH, and SPLH is what turns next week's schedule from a hunch into something you can check afterwards.
Related Articles
Margin vs Markup in Retail Math
A buyer and a controller report different margins on the same category and both are right. Where the two conventions came from, which metrics mislead and when, and how to decide which number has authority.
Read article
The Retail KPI Guide: 18 Metrics Every Store Should Track
A practical reference of the 18 retail KPIs that actually move the business, with formulas, benchmarks, and how to use each one.
Read article
GMROI Explained: The Cornerstone Profitability Metric for Retail Buyers
The most honest profitability metric in retail. How buyers and category managers actually use GMROI to make cross-category assortment, pricing and open-to-buy decisions.
Read article
Inventory Turnover Explained: Formula, Benchmarks and How to Actually Move It
How retail operators actually work the turnover ratio. The formula, the cost-versus-sales trap, three what-if scenarios, category benchmarks, the seven levers that move turn, and the guardrails that keep higher turn from becoming lost sales.
Read article
Explore Related Resources
Handpicked benchmarks, templates and guides to help you dig deeper.
Related Retail Metrics
Five core calculators every buyer, merchandiser and category manager reads together. Open the metric that is behind, and let the others sanity-check it.
Gross Margin Calculator
Percent of revenue kept after paying for the goods. The anchor number on the retail P&L.
Open calculator
Markup Calculator
Percent added on top of cost to reach the selling price. The buyer’s pricing language.
Open calculator
GMROI Calculator
Gross profit per dollar of average inventory. The honesty check on margin and turnover.
Open calculator
Sell-Through Rate Calculator
Units sold as a percent of units received. The leading indicator for markdown timing.
Open calculator
Inventory Turnover Calculator
How many times average inventory sells through in a year. The core inventory KPI.
Open calculator